Purpose, product and commercial model
Inside Seller Finance.
Seller-financed property acquisition and disposal model
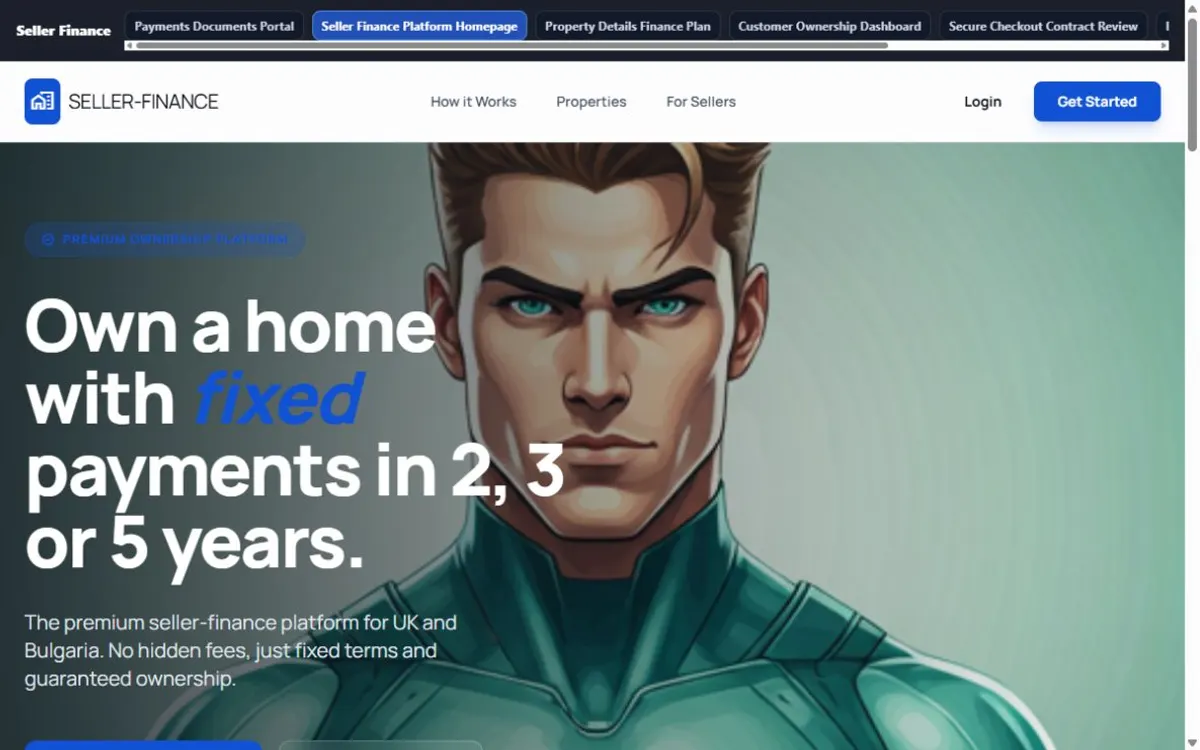
Seller Finance is planned as a property operating platform for acquiring undervalued European homes and reselling them through legally structured instalment, lease-option or contract-for-deed arrangements. Buyers pay an upfront administration or option fee followed by fixed monthly payments, with title transferring after the agreed amount is satisfied. The model is intended to combine immediate fees, recurring cashflow and backend capital gain while widening access for income-capable buyers outside conventional mortgage underwriting. Every jurisdiction and contract structure requires specialist legal, tax and compliance review.
Who the business serves
The intended audience includes buyers who can meet an agreed payment schedule but cannot use a conventional mortgage route, alongside operators sourcing suitable property. Geographic expansion is jurisdiction-specific. The digital brand supports explaining an offer and managing enquiries; it does not itself establish an owned property portfolio.
Product and operating model
The plan describes buying property and offering an appropriately documented instalment or lease-option arrangement. Occupation, title transfer, maintenance responsibilities and payment milestones must follow the actual contract. The operating model depends on property due diligence, suitable legal documentation and ongoing servicing. It should be assessed as a proposed property business rather than a generic software subscription.
Intended revenue streams
The commercial model below describes the intended ways this business can earn income. It does not represent verified sales, customers or recurring revenue.
- Agreed setup or option fees
- An appropriately disclosed upfront fee can be part of the specific contractual product.
- Contractual instalments
- Recurring buyer payments arise from completed property agreements, rather than from website traffic.
- Property disposal contribution
- The difference between acquisition, operating costs and the agreed disposal outcome is the intended asset-level commercial result.
Development intentions
Prove a lawful, maintainable transaction structure and complete property economics before repeating the model. The archived plan's optimistic return assumptions are omitted. The sale must state whether it includes only the brand and operating materials or any actual property, contracts and servicing rights; those assets cannot be inferred from the site.
Description basis: Business-plan review, reconciled with the current portfolio direction.
Reviewed 7 October 2026. The sections explain product direction and commercial intentions. Delivered features, active agreements and earnings are assessed separately during acquisition.